Avoid Six Month Medicare Backdating That Stops HSA Contributions, U.S.
No, you cannot make new HSA contributions once you’re enrolled in any part of Medicare. Your existing HSA balance stays yours, though, and it still covers many Medicare costs tax-free, including Part B, Part D, and Medicare Advantage premiums. The one major exception is Medigap. Those supplement premiums don’t qualify, no matter how much money sits in your account.
TL;DR:
- Contributions to an HSA must stop the month you enroll in any part of Medicare, even if you are still working and have high deductible health coverage.
- Once enrolled in Medicare, HSA funds can still cover Part B, Part D, Medicare Advantage premiums, deductibles, copays, coinsurance, and certain health costs, but not Medigap premiums.
- Retroactive Medicare coverage of up to six months can make previously legal HSA contributions excess, leading to potential tax penalties if not corrected before filing taxes.
- To avoid excess contributions, stop HSA deductions at least two to three months before applying for Medicare, especially if applying for Social Security benefits that trigger automatic enrollment.
- Calculate prorated annual contribution limits based on months before Medicare enrollment and withdraw excess funds with earnings before tax deadlines to prevent penalties.
Core Insurance SolutionsGet Medicare Guidance That FitsCore Insurance Solutions helps Lakeland seniors compare Medicare options around their health needs, prescriptions, and ongoing coverage decisions.Visit Core Insurance Solutions
Table of Contents
- What Changes When You Enroll in Medicare (Eligibility and Contribution Rules)
- What You Can Still Pay With HSA Funds After Medicare Begins
- The Retroactive Enrollment Trap and Timing: Why Contributions You Made Can Become Excess
- How to Calculate Prorated Contribution Limits and Correct Excess Contributions
- Action Checklist: Steps to Take Before and After Enrolling in Medicare
- Core Insurance Solutions: How We Help Clients Coordinate HSAs and Medicare Enrollment
- If You Want Help: Schedule a Consult or Use Our Tools
- Authoritative Primary Sources
- Sources
- FAQ
What Changes When You Enroll in Medicare (Eligibility and Contribution Rules)
Age has nothing to do with it. Enrollment does. The moment you’re enrolled in any part of Medicare, whether that’s Part A, B, C, or D, your HSA contribution limit drops to zero starting that same month, according to IRS Publication 969. It doesn’t matter if you’re still working full time with a high deductible health plan through your employer. Once Medicare enrollment kicks in, new contributions stop being allowed.
This trips people up because being eligible for Medicare and being enrolled in Medicare are two different things. Turning 65 makes you eligible. It doesn’t automatically enroll you, unless you’re already collecting Social Security benefits, in which case Part A enrollment happens automatically. Here’s where it gets trickier: premium-free Part A still counts as full enrollment for HSA purposes, even though you’re not paying anything for it. A lot of people assume that because there’s no premium, it doesn’t “count.” It counts.
A few scenarios determine how this plays out in practice:
- If you’re collecting Social Security before or at 65, Part A enrollment happens automatically, and your HSA contribution window closes that same month.
- If you delay claiming Social Security and stay covered by an employer’s HDHP, you can typically delay Medicare enrollment and keep contributing.
- If you sign up for Part A only, without Part B, you still lose HSA eligibility, since Part A alone counts as enrollment.
- If your employer coverage is considered creditable and you have fewer than 20 employees, Medicare rules interact differently, and you should check with your HR department before assuming you can delay.
Medicare walks through exactly how Social Security filings trigger automatic Part A enrollment, which is worth reading before you file anything.
What You Can Still Pay With HSA Funds After Medicare Begins
Losing the ability to contribute doesn’t mean losing the account. Every dollar already sitting in your HSA remains yours, and it keeps its tax-free status for qualified medical expenses, based on IRS guidance on tax-favored health plans. Here’s what still qualifies once Medicare has started:
- Part A premiums, if you’re one of the relatively few people who pay them (most don’t, since Part A is premium-free for anyone with sufficient work history).
- Part B premiums, which everyone pays, and which you can reimburse directly from your HSA.
- Part D premiums, covering your prescription drug plan.
- Medicare Advantage premiums, for anyone who chooses a Part C plan instead of Original Medicare.
- Deductibles, copays, and coinsurance tied to any qualified Medicare service.
- Dental, vision, and hearing costs that meet the IRS definition of a qualified medical expense.
What doesn’t qualify: Medigap, also called Medicare Supplement, premiums. The IRS explicitly excludes these from the list of qualified medical expenses, so paying them from your HSA triggers ordinary income tax plus a possible penalty if you’re under 65. If you’re weighing supplement coverage against Medicare Advantage, it’s worth understanding how Medigap plans work before you assume your HSA can help cover the premium.
One detail that surprises a lot of retirees: you can reimburse yourself for premiums you already paid, even ones deducted straight from your Social Security check, according to Kiplinger’s coverage of HSA reimbursement rules. Keep your Social Security benefit statements and Part B premium notices. Without documentation, you can’t prove the reimbursement was for a qualified expense if the IRS ever asks.
The Retroactive Enrollment Trap and Timing: Why Contributions You Made Can Become Excess
This is the part almost nobody warns you about until it’s too late. When you apply for Medicare Part A after your 65th birthday, coverage can backdate up to six months, though never earlier than the month you turned 65, according to Indiana University’s HR guidance on Medicare and HSAs. That backdating is the trap. Any HSA contribution you made during those retroactive months, contributions that were perfectly legal when you made them, instantly become excess contributions once Medicare coverage is applied retroactively.
It’s not a one-time slap on the wrist. It compounds.
A few situations create this problem more often than people expect:
- Applying for Social Security retirement benefits several months after turning 65, which pulls Part A enrollment backward to cover the gap.
- Assuming automatic Part A enrollment only applies going forward, when it can reach back up to six months.
- Continuing payroll HSA deductions on autopilot because nobody told HR to stop them.
Pro Tip: Mark your 65th birthday minus six months on your calendar the day you decide to delay Medicare. If you plan to file for Social Security or Part A anywhere near that window, stop HSA contributions before you apply, not after.
How to Calculate Prorated Contribution Limits and Correct Excess Contributions
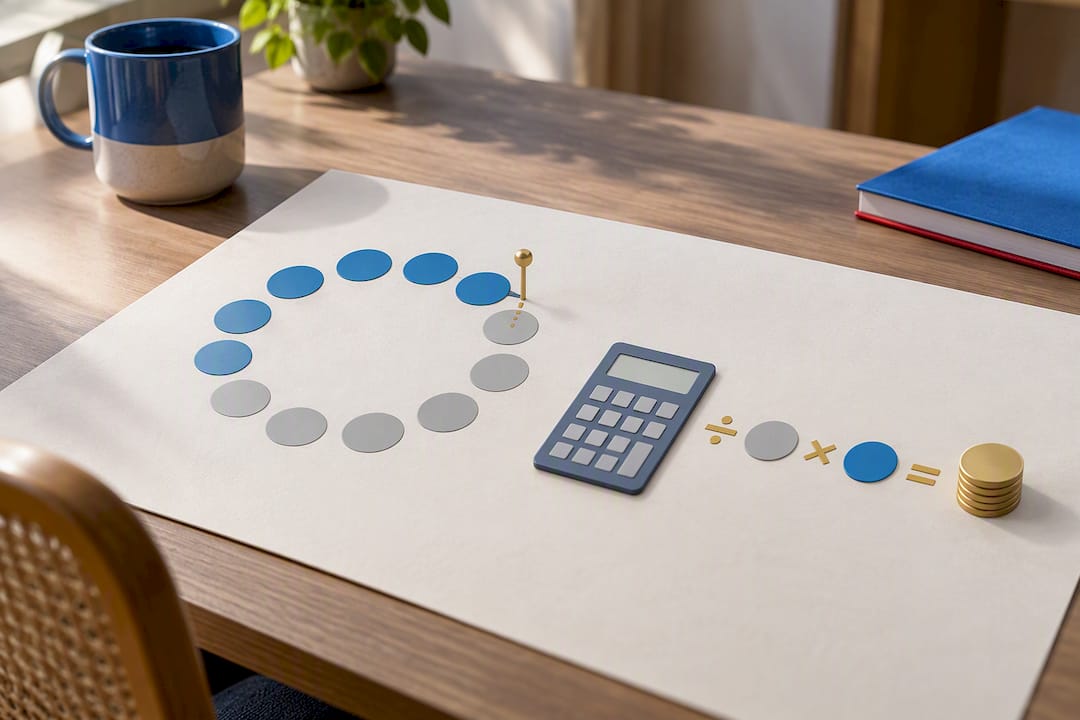
In the year you enroll in Medicare, your annual HSA contribution limit gets prorated based on the number of months you were HSA-eligible before enrollment began. Divide the full-year limit by 12, multiply by the number of eligible months, and that’s your ceiling for the year, reported on Form 8889.
There’s an exception worth knowing: the “last-month rule” lets you contribute the full annual limit if you’re HSA-eligible on December 1, but it locks you into a testing period through the following December 31. Enroll in Medicare during that testing period and you’ll owe back the extra contribution as taxable income.
If you’ve already over-contributed:
- Withdraw the excess amount plus any earnings on it before your tax-filing deadline, and the 6% excise tax disappears entirely, per IRS Publication 969.
- Miss that window, and you’ll file Form 5329 to calculate and report the excise tax owed.
- Use Form 8889 every year you have HSA activity, and talk to a tax professional if the timing overlaps a Medicare enrollment year.
Action Checklist: Steps to Take Before and After Enrolling in Medicare
Get the order right and this whole process is manageable. Get it wrong and you’re filing extra tax forms for years. Financial advisors typically recommend halting contributions several months before applying for Medicare rather than waiting until enrollment is finalized.
- Decide whether delaying Medicare makes sense, based on your employer’s HDHP coverage and how much you still want to contribute to your HSA.
- Stop new HSA contributions at least two to three months before you apply for Medicare or Social Security, since retroactive coverage can reach back that far.
- Tell payroll directly to stop automatic HSA deductions. Don’t assume enrollment paperwork handles this for you.
- Save every receipt for Medicare premiums and qualified expenses so you can reimburse yourself later without a paper-trail problem.
- If retroactive coverage catches you anyway, withdraw the excess contribution before the tax-filing deadline, or file Form 5329 and talk to a tax advisor about the excise tax.
Review our step-by-step enrollment guide alongside this checklist, since enrollment paperwork and HSA timing need to move together, not separately.
Core Insurance Solutions: How We Help Clients Coordinate HSAs and Medicare Enrollment
We built our Holistic Health Needs Assessment around exactly this kind of timing problem. Seniors rarely come asking about HSA rules specifically. They come asking about Medicare plans, and the HSA question surfaces once enrollment dates and savings are reviewed. Employer coverage, Social Security timing, and HSA balances are considered before making recommendations.
Bring your HSA statements and premium receipts to a consultation. It changes the conversation from guesswork to a real plan, and many clients return for annual policy reviews.
— Core Insurance Solutions
If You Want Help: Schedule a Consult or Use Our Tools
Getting Medicare timing wrong costs real money, whether it’s an excise tax on excess HSA contributions or a Medigap premium you assumed your HSA would cover. We work through this timing directly, helping clients compare carriers and identify when HSA contributions should stop before applying for Medicare.
Our enrollment timeline tool maps out your specific dates so you’re not guessing at the six-month retroactive window on your own. If you’d rather start with education before a conversation, our free Medicare 101 webinar replay covers enrollment timing and plan tradeoffs at your own pace. When you’re ready to talk through your specific situation, including how to optimize prescription costs and coordinate an existing HSA balance, our full services page outlines how a consultation works and how to book one.
Authoritative Primary Sources
For the official, current numbers behind everything above, go straight to the source:
- IRS Publication 969, covering HSA eligibility, contribution limits, and qualified medical expenses.
- Medicare, covering enrollment periods and effective dates.
This article is general information, not a substitute for advice from a qualified doctor. Consult a qualified healthcare professional about your own circumstances before acting on anything here.
Sources
FAQ
What happens if you have an HSA and Medicare?
Once Medicare enrollment begins, your HSA contribution limit drops to zero, but your existing balance remains usable tax-free for qualified expenses, according to IRS Publication 969. You keep the account and the money. You just can’t add to it anymore.
Do you have to stop HSA contributions six months before Medicare?
Not exactly six months by rule, but it’s smart practice, since Part A enrollment can backdate up to six months once you apply, per guidance from Indiana University HR. Stopping contributions a few months ahead of applying protects you from that retroactive window turning prior contributions into excess ones.
Can you contribute to an HSA after 65 if you are not on Medicare?
Yes. If you delay Medicare enrollment and stay covered by a qualifying high deductible health plan, typically through continued employment, you can keep contributing past 65. The rule is tied to Medicare enrollment status, not your age.
Can I pay my spouse’s Medicare premiums with my HSA?
Yes, HSA funds can cover a spouse’s Medicare premiums, including Part B and Part D, as long as they qualify as your tax dependent or spouse under IRS rules for qualified medical expenses. Medigap premiums still don’t qualify, even when paid for a spouse.
Can HSA funds pay for Medigap premiums?
No. The IRS specifically excludes Medigap, or Medicare Supplement, premiums from qualified medical expenses for HSA distributions. Paying them from an HSA triggers ordinary income tax on the withdrawal.


