0.75%–1.25% Rider Fees: Fixed Indexed Annuities for U.S. Seniors
A fixed indexed annuity is an insurance contract that credits interest tied to a market index while guaranteeing you won’t lose principal from market declines. It typically fits conservative-to-moderate near-retirees who want more growth potential than a CD but can’t stomach direct stock market losses. The trade-off is real: you give up a slice of the upside in exchange for that floor, and understanding exactly how much upside you’re giving up is the whole game.
TL;DR:
- The effective return gap of roughly 1.1% to 1.5% annually compared to owning the index directly can significantly impact long-term growth, especially over a decade.
- The credited interest depends on the method used, with annual point-to-point locking in gains, while monthly averaging and summing can limit upside or result in zero interest in volatile years.
- Most contracts feature surrender periods of 5 to 10 years, with penalties such as market value adjustments and IRS penalties for early withdrawals, reducing liquidity.
- Guarantees, including income riders, often come with additional fees of 0.75% to 1.25% annually, and their benefits depend on the contract terms and rider activation rules.
- Insurer strength ratings and understanding cap renewal histories are crucial, as product guarantees rely on the financial stability of the issuing company.
Table of Contents
- What Is a Fixed Indexed Annuity?
- How Fixed Indexed Annuities Credit Interest
- Weighing the Pros and Cons
- Income Riders and Guaranteed Lifetime Withdrawal Benefits
- What FIAs Actually Cost You
- Insurer Strength and Regulatory Protections
- A Decision Checklist Before You Buy
- Death Benefit and Beneficiary Options
- FIAs vs. Variable Annuities, Fixed Annuities, and Mutual Funds
- Inflation Risk and How to Manage It
- Core Insurance Solutions’ Approach to FIAs for Seniors
- Get Personalized Guidance on Retirement Income and Medicare
- Sources
What Is a Fixed Indexed Annuity?
A fixed indexed annuity, or FIA, is not a stock, mutual fund, or brokerage product. It’s a contract with an insurance company. You hand the insurer a lump sum (or a series of payments), and the insurer promises two things: your principal won’t decline because of a bad year in the market, and your account will grow when the linked index performs well, up to certain limits.
That second part matters. Indexed annuities are insurance products, not securities, which means they’re regulated at the state level rather than by the SEC. You’re not buying the S&P 500. You’re buying a promise from an insurer to calculate a credit based on how that index moves.
An FIA ties interest credits to a market index while guaranteeing principal cannot decline due to index losses. The math behind that credit is where most buyers get confused, so here’s the breakdown:
- Accumulation phase: your money grows tax-deferred, meaning you owe nothing on gains until you withdraw them.
- Distribution phase: you either take lump-sum withdrawals, annuitize into a stream of payments, or activate an income rider (more on that below).
- Zero floor: in a year the index drops, your credited interest is 0%, not negative. You don’t lose ground, but you don’t gain any either.
Tax deferral is one of the more underappreciated features here, especially for someone already juggling Medicare premiums, Social Security taxation thresholds, and required minimum distributions from other accounts.
How Fixed Indexed Annuities Credit Interest
This is the part that trips people up, and honestly, it’s the part carriers don’t always explain clearly in a sales pitch. Your credited interest depends on which crediting method the contract uses, and each one behaves differently depending on how choppy the market gets.
- Annual point-to-point. The insurer compares the index value on your contract anniversary to the value one year earlier. Gains within your cap or participation rate get credited, then the anniversary date resets, or “ratchets,” so prior gains are locked in and can’t be taken back even if the index crashes the following year.
- Monthly average. The insurer averages the index’s value across 12 monthly readings, then compares that average to the starting point. This method tends to smooth out volatility, which helps in choppy years but can leave money on the table during a strong, steady climb.
- Monthly sum. Each month’s percentage change gets capped individually, then all 12 monthly figures are added together. The catch: positive months are capped, but negative months are not. A volatile year with several strong up months and a couple of sharp down months can produce a credited interest rate of 0% even when the index finished the year higher.
- Multi-year point-to-point. Some contracts measure performance over two or three years instead of one, and carriers sometimes offer stronger caps or participation rates in exchange for the longer measurement window.
Fast fact: Because FIAs typically credit interest based on index price movement alone, excluding dividends, the effective return gap versus owning the index directly runs roughly 1.1% to 1.5% annually, depending on the index’s dividend yield. That’s a meaningful drag over a decade.
Three levers determine how much of the index’s move you actually keep:
- Cap rate: the maximum interest rate you can earn in a crediting period, regardless of how high the index climbs.
- Participation rate: the percentage of the index’s gain you’re credited. An 80% participation rate on a 10% index gain credits you 8%.
- Spread: a fee subtracted from the index gain before your credit is calculated, similar to a haircut off the top.
Carriers can reset caps and participation rates at renewal, often annually after an initial guarantee period. A contract that opens with an attractive 9% cap can renew at 5% two years later, which is why asking about a carrier’s historical renewal behavior matters more than the number printed in year-one marketing material.
Weighing the Pros and Cons
No retirement product is free of trade-offs, and FIAs come with a distinct set of both.
What works in their favor:
- Principal protection against index losses, so a market crash doesn’t erase your account value.
- Tax-deferred growth until withdrawal.
- Upside participation in rising markets, unlike a plain fixed annuity or CD with a locked rate.
- Optional lifetime income riders that guarantee payments you can’t outlive.
Where they fall short:
- Upside is capped, participation-limited, or spread-reduced, so you rarely capture a full bull-market year.
- Costs are often embedded in the crediting formula itself rather than shown as a line-item fee, plus separate rider charges if you add one.
- Surrender periods commonly run 5 to 10 years, which limits access to your full balance.
- Contracts are genuinely complex, with terms that vary meaningfully from one carrier to the next.
Compared with a CD, an FIA usually offers more upside potential and tax deferral, but less liquidity. Compared with a multi-year guaranteed annuity (MYGA), an FIA trades a locked-in fixed rate for the chance at higher, market-linked returns. Compared with direct index fund ownership, an FIA sacrifices dividend income and full upside for a guarantee against loss.
Pro Tip: Ask any FIA salesperson to show you the contract’s actual historical renewal caps, not just the current one. A carrier that’s cut its cap rate three years running tells you more than any brochure.
Income Riders and Guaranteed Lifetime Withdrawal Benefits
Many FIAs offer an optional guaranteed lifetime withdrawal benefit (GLWB) rider, which promises income you can’t outlive regardless of how the underlying account performs. It’s a separate feature from the base contract, and it’s worth understanding before you assume it’s automatically included.
- The rider tracks a separate income base, distinct from your actual account value, that often grows by a contractual roll-up rate (commonly 5% to 8% annually) during the deferral years before you start withdrawals.
- Rider fees typically run 0.75% to 1.25% annually, deducted from your account value, which quietly reduces the money actually available for lump-sum access or a death benefit.
- Withdrawals above the guaranteed percentage can reduce or void future income guarantees, so understand the withdrawal limits before you touch extra cash.
- Joint-life options extend guaranteed payments across both spouses’ lifetimes, usually at a lower payout percentage than a single-life election.
Riders make the most sense for someone who wants a pension-like income stream and is comfortable trading some liquidity and cost for that certainty. If you don’t need guaranteed lifetime income, skipping the rider avoids a fee for a benefit you’ll never use.
What FIAs Actually Cost You
Surrender charges are the most visible cost. Most contracts carry a surrender schedule lasting several years, with charges that start relatively high in the first year and decline to zero by the end of the period.
- Most contracts allow free withdrawals of 10% annually without penalty, even during the surrender period.
- A market value adjustment (MVA) can apply if you withdraw beyond the free amount during the surrender period. It adjusts your withdrawal value up or down based on interest rate movement since you bought the contract, similar to how bond prices move opposite interest rates.
- Explicit fees mostly come from riders; the rest of the cost is embedded in the caps, participation rates, and spreads that determine your credited interest.
- Withdrawals before age 59½ typically trigger a 10% IRS penalty on the taxable portion, on top of ordinary income tax.
Insurer Strength and Regulatory Protections
An FIA is only as good as the company standing behind it. Unlike bank deposits insured by the FDIC, annuity guarantees rely on the insurer’s own financial strength, backed by state guaranty associations that provide limited protection if a carrier fails.
- Check a carrier’s financial strength ratings from agencies like A.M. Best, Moody’s, or S&P before signing anything. This single step catches more problems than any other.
- Actuarial guidance including AG33 and AG35 shapes how carriers calculate statutory reserves for FIA guarantees, which affects how conservatively (or aggressively) a company prices its products.
- State guaranty associations cap coverage per policyholder, and those limits vary by state, so a very large annuity purchase might not be fully protected.
- Watch for red flags: proprietary indices with no public track record, unusually high initial roll-up rates that seem designed to lure you in, and vague language about how caps get set at renewal.
A Decision Checklist Before You Buy
Run through this before signing anything, ideally with an advisor who isn’t only paid to sell you the annuity in front of you.
- Confirm your time horizon. FIAs generally fit money you won’t need for 7 to 10 years or more, given surrender schedules and MVA exposure.
- Request the actual contract terms, not a hypothetical illustration. Get the current cap, participation rate, or spread, plus the carrier’s renewal history on those numbers over the past five to ten years.
- Run sample scenarios. Ask for credited-return illustrations under flat, rising, and volatile market conditions, then compare those numbers against a CD, a MYGA, or a simple index fund allocation.
- Ask direct questions about riders. What’s the fee? How does the income base grow? What triggers activation, and what happens to the death benefit once income starts?
Pro Tip: Bring your Medicare Part B and Part D premium estimates into this conversation. If you’re near the income thresholds for IRMAA surcharges, how you structure annuity withdrawals can bump you into a higher premium bracket without you realizing it until the bill arrives.
Death Benefit and Beneficiary Options
Most FIAs include a standard death benefit equal to the account value, paid to your named beneficiary if you die before annuitizing or fully withdrawing the contract. That’s often the full accumulated value, not a reduced amount, which distinguishes FIAs from some annuitized income streams that stop paying when you die.
Some contracts offer an enhanced death benefit rider for an added cost, which can pay out a higher amount than the base account value, sometimes calculated using the income rider’s roll-up base instead of the actual cash value. If you’ve activated a GLWB and started taking lifetime withdrawals, the death benefit at that point typically reflects whatever account value remains, which can be significantly less than the original deposit if you’ve been drawing income for years.
Naming a beneficiary properly matters more than most people realize. A spouse named as beneficiary can often continue the contract under spousal continuation rules, preserving the tax-deferred status rather than forcing a lump-sum taxable payout. A non-spouse beneficiary usually faces different distribution rules and a tighter timeline for withdrawing the funds, which can trigger a larger tax bill in a single year than the family expected.
Review your beneficiary designations any time your family situation changes, a divorce, remarriage, or the death of a previously named beneficiary. An outdated designation can send your annuity’s value to an ex-spouse or force it through probate instead of passing directly, which defeats one of the biggest practical advantages of owning an annuity in the first place.
FIAs vs. Variable Annuities, Fixed Annuities, and Mutual Funds
Each of these products solves a different problem, and the differences matter more than the marketing suggests.
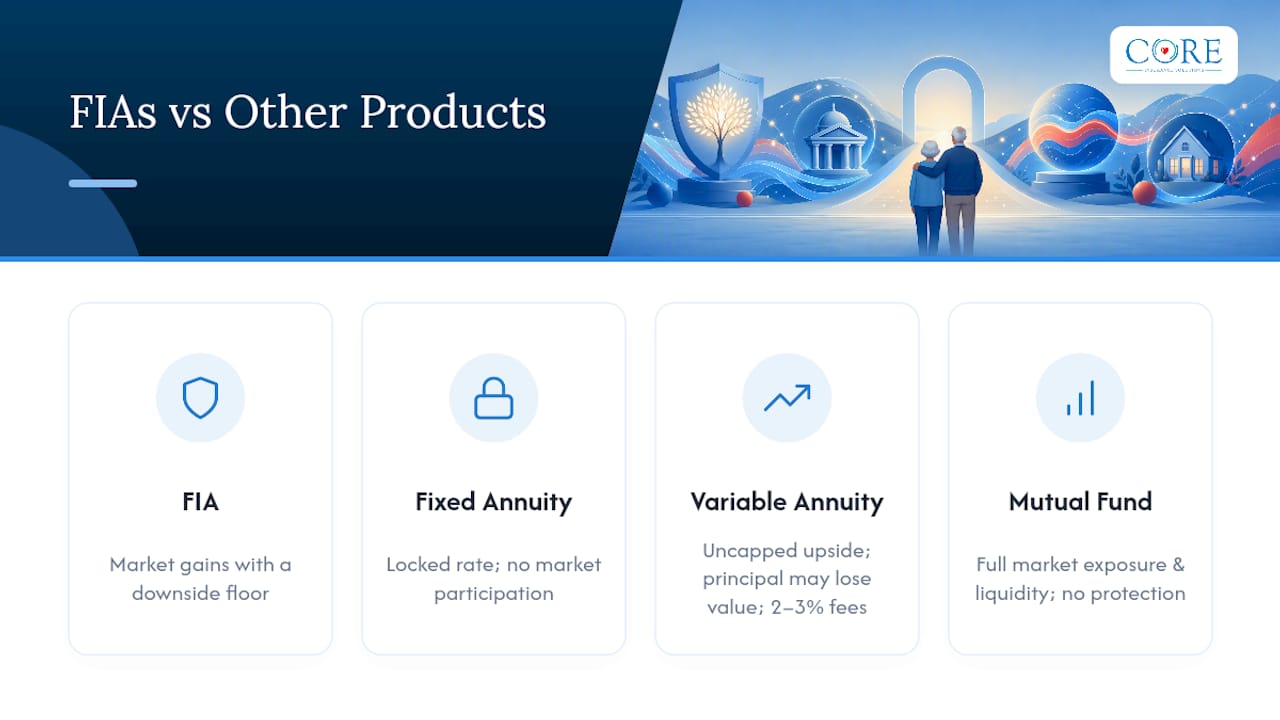
A fixed annuity (sometimes called a MYGA) pays a locked-in interest rate for a set term, with no market participation at all. It’s simpler and more predictable than an FIA, but you sacrifice any chance at higher returns if the market performs well. If your only goal is a guaranteed rate with zero complexity, a fixed annuity is the more straightforward tool.
A variable annuity invests your premium in subaccounts similar to mutual funds, meaning your principal can actually lose value in a market downturn. In exchange, you get uncapped upside potential and, often, more rider flexibility. Variable annuities also tend to carry higher fees, sometimes 2% to 3% annually between mortality charges, administrative fees, and fund expenses, on top of any rider costs.
A mutual fund or index fund held in a brokerage account gives you full market exposure, dividends included, with no cap on gains and no insurance company standing between you and the index. You also get full liquidity. What you don’t get is any protection against a downturn. A retiree who needs guaranteed income or can’t tolerate a 30% drawdown right before retirement often values the FIA’s floor more than the mutual fund’s unlimited upside.
The right mix usually isn’t all one or the other. Many retirees layer an FIA for a guaranteed income floor alongside mutual fund holdings for longer-term growth, letting each product do the job it’s actually built for.
Inflation Risk and How to Manage It
Inflation is the quiet threat that FIA marketing rarely addresses head-on. A capped credited rate that looked generous in a low-inflation year can lose real purchasing power fast when prices rise faster than your credited interest.
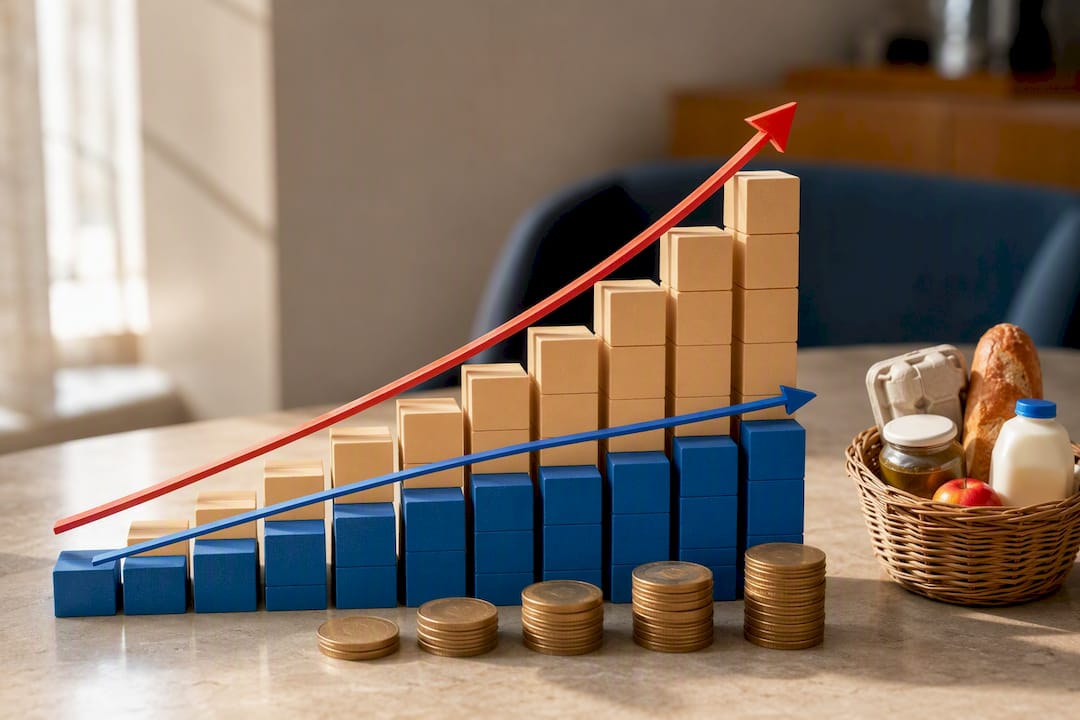
If your FIA credits 5% in a year when inflation runs at 4%, your real gain is thin. If a future year credits 0% (which happens whenever the index falls or a monthly-sum method zeroes out on volatility) while inflation keeps climbing, your purchasing power erodes even though your account balance didn’t drop.
A few practical ways to manage that risk:
- Don’t put your entire retirement nest egg into one FIA. Keep a portion in assets with more consistent long-term inflation-beating potential, like diversified equity funds.
- Consider an income rider with a cost-of-living adjustment (COLA) option if the carrier offers one, understanding that it usually reduces your starting payment in exchange for future increases.
- Reassess your Medicare and supplemental coverage costs annually, since healthcare inflation frequently outpaces general inflation and can quietly eat into fixed income streams. Coordinating that review with your Medicare Supplement coverage helps you catch cost creep before it becomes a bigger problem.
- Ladder multiple guaranteed products with different start dates instead of committing all your retirement savings to a single contract at a single point in the rate cycle.
Core Insurance Solutions’ Approach to FIAs for Seniors
We don’t treat an FIA as a standalone decision. Retirement income and Medicare costs are connected, so we build annuity recommendations into the same conversation as your annual policy audit, checking how withdrawal timing might affect IRMAA thresholds or premium budgeting. We push for transparent illustrations built on a carrier’s actual renewal history, not just the number printed in year-one marketing, and we check insurer financial strength before we ever recommend a contract. and.
— Core Insurance Solutions
Get Personalized Guidance on Retirement Income and Medicare
Choosing between an FIA, a MYGA, or keeping your money in the market isn’t a decision to make from a brochure, and it’s not one you have to make alone. Core Insurance Solutions built its practice around exactly this kind of coordinated planning, connecting retirement-income decisions to the Medicare choices most seniors are juggling at the same time.
We serve seniors throughout the Lakeland, FL area, including Winter Haven, Auburndale, Bartow, and surrounding communities, with a holistic health needs assessment that looks at your full financial and medical picture before recommending anything. If you’re weighing a retirement-income product against your Medicare enrollment timeline, our free Medicare 101 webinar replay walks through exactly how those pieces fit together. Ready for a straight answer about your specific situation? Schedule a retirement-income review and we’ll walk through your options carrier by carrier, with no pressure to sign anything on the first call.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- What Is a Fixed Index Annuity? How FIAs Work
- Fixed indexed annuities—product mechanics and risk management
- Fixed indexed annuity pros and cons (USAA)
- Investor


