Chiropractic Medicare Coverage: Avoid Denials and Surprise Bills
Original Medicare (Part B) covers exactly one chiropractic service: manual spinal manipulation to correct a vertebral subluxation. Everything else a chiropractor orders, from x-rays to massage, comes out of your pocket. Once you meet the Part B deductible, Medicare pays 80% of the approved amount for that manipulation, leaving you responsible for the coinsurance portion.
TL;DR:
- Medicare covers only manual spinal manipulation for vertebral subluxation correction, billed under specific CPT codes, and does not include other chiropractic services.
- Out-of-pocket costs depend on whether the chiropractor participates in Medicare, with coinsurance potentially increasing if the provider is non-participating.
- Diagnostic imaging ordered by chiropractors is generally not covered unless done by a physician, so it’s better to have your primary doctor request X-rays if needed.
- Proper documentation showing a specific, treatable spinal issue with exam findings or imaging is essential to avoid claim denials.
- Verifying the chiropractor’s Medicare participation and ensuring they use an active treatment AT modifier can significantly improve the chances of claim approval and lower costs.
Table of Contents
- What Does Chiropractic Medicare Coverage Actually Include?
- What Will You Pay Out of Pocket?
- Which Chiropractic Services Aren’t Covered by Medicare?
- Why Do Medicare Chiropractic Claims Get Denied?
- How Should You Set Up Chiropractic Care to Get Covered?
- Does Medicare Advantage or Medigap Change Your Chiropractic Coverage?
- What Should You Watch For Before Your Next Visit?
- Where Can You Verify These Chiropractic Coverage Rules?
- An Honest Take on Chiropractic Medicare Coverage
- Sources
What Does Chiropractic Medicare Coverage Actually Include?
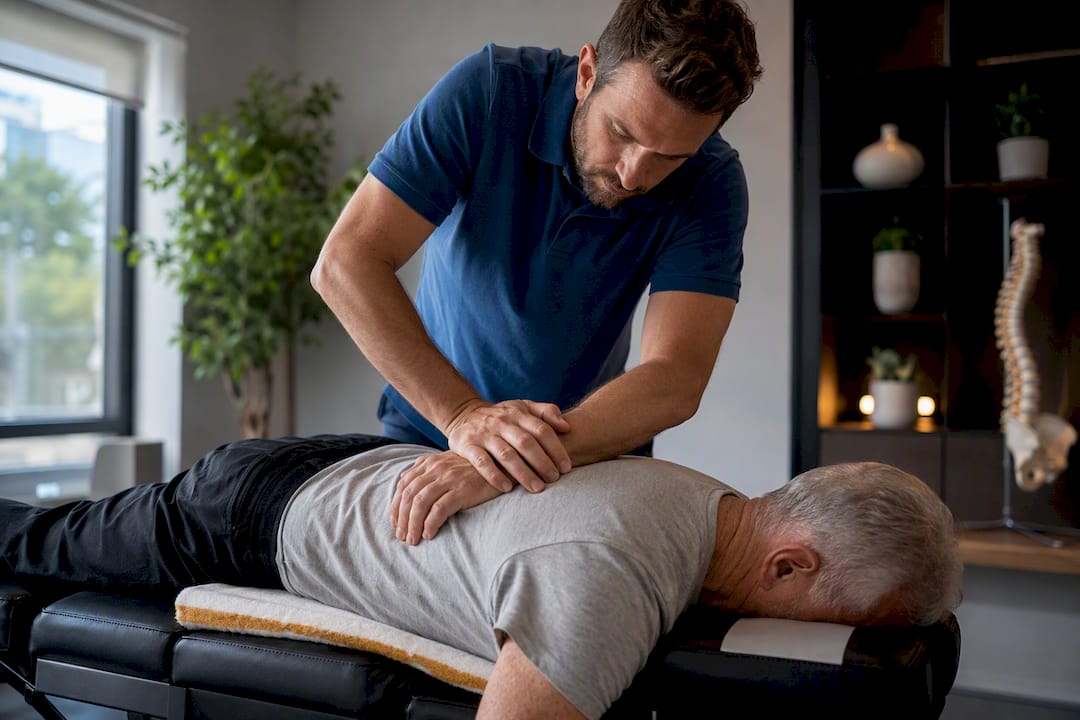
Medicare’s chiropractic benefit is narrower than most people assume. It pays only for manual manipulation of the spine performed by hand, aimed at correcting a vertebral subluxation, which is essentially a misalignment of the vertebrae that Medicare considers medically significant enough to treat.
You’ll see this billed under one of three CPT codes: 98940, 98941, or 98942, depending on how many spinal regions the chiropractor treats. These codes don’t affect your care directly, but recognizing them on a bill or Medicare Summary Notice helps you confirm you’re being charged for a covered service rather than something else lumped into the same visit.
A few boundaries matter here:
- Coverage applies to the spine only. Medicare does not pay for manipulation of the arms, legs, or other joints.
- X-rays can be used to document the subluxation, but Medicare will not pay for an x-ray ordered by the chiropractor themselves.
- The subluxation must be demonstrated, either through a physical exam finding or imaging, not simply asserted on a claim form.
That last point trips up a lot of beneficiaries. A chiropractor can’t bill Medicare just for “back pain” or general wellness adjustments. The record has to show a specific, correctable spinal problem.
What Will You Pay Out of Pocket?
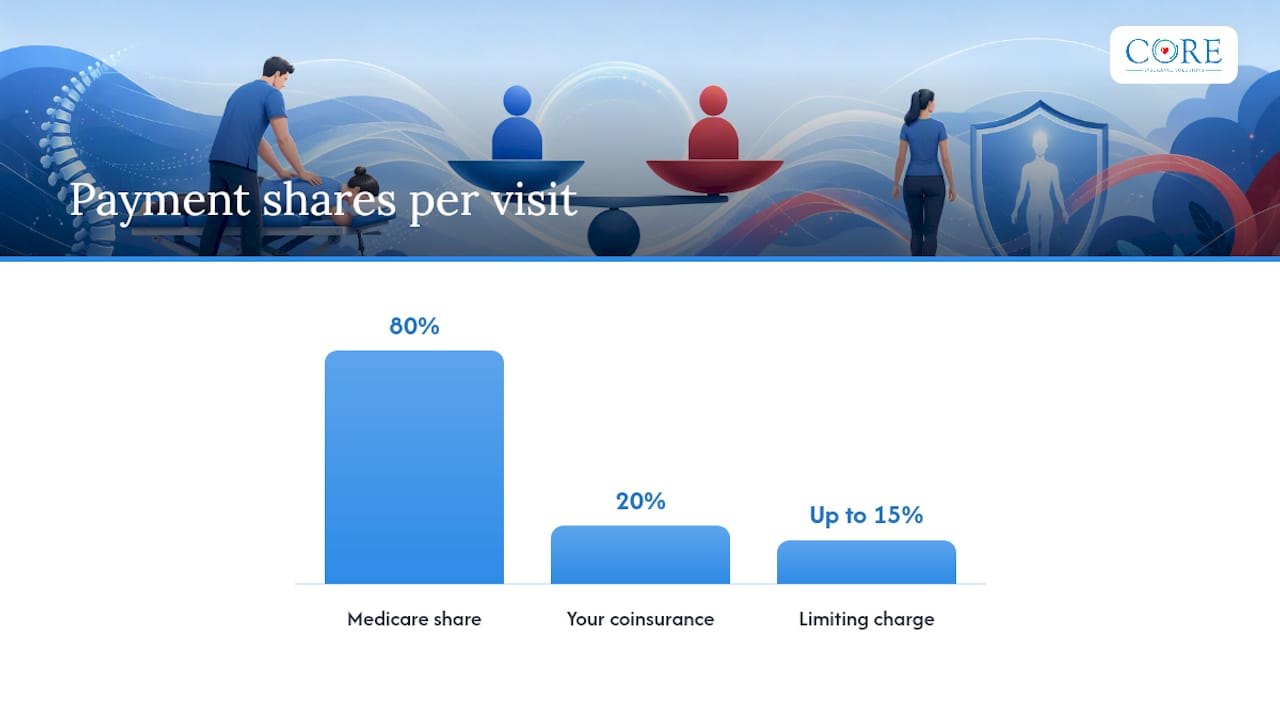
The math is straightforward once you know the pieces. You pay the annual Part B deductible first, then 20% coinsurance on the Medicare-approved amount for each covered visit, and Medicare covers the remaining 80%.
Who your chiropractor is matters more than most patients realize:
- A participating provider agrees to accept the Medicare-approved amount as full payment, so your 20% is predictable.
- A non-participating provider can charge up to 15% more than the approved amount, known as the limiting charge, which raises your share of the bill.
- Approved amounts for spinal manipulation are relatively modest per visit, but frequent treatment adds up fast if you’re paying 20% every time.
Pro Tip: Ask the front desk whether the chiropractor participates in Medicare before your first appointment. It’s a two-minute question that can save you real money over a course of treatment.
Which Chiropractic Services Aren’t Covered by Medicare?
Beyond spinal manipulation, Medicare draws a hard line. Here’s what you’ll typically pay for entirely yourself when a chiropractor orders or performs it:
- X-rays and diagnostic imaging ordered by the chiropractor, even when used to support the same visit’s treatment.
- Extraspinal manipulation (CPT 98943), meaning adjustments to the shoulders, hips, knees, or other non-spinal joints.
- Massage therapy, acupuncture, and electrical stimulation, regardless of whether they’re bundled into a chiropractic visit.
- Supplies, supplements, or nutritional counseling offered through a chiropractic office.
- Maintenance therapy, which CMS defines as treatment that no longer produces measurable improvement.
Here’s the workaround worth knowing: an x-ray Medicare won’t pay for when a chiropractor orders it can be covered when a physician orders the same imaging. If you need diagnostic imaging, ask whether your primary care doctor can order it instead. And before any visit, simply ask the office directly whether they’ll bill Medicare for a given service or expect you to pay privately. Chiropractic offices vary widely in how transparent they are about this upfront.
Why Do Medicare Chiropractic Claims Get Denied?
Documentation, not treatment quality, is the biggest reason chiropractic claims fail. CMS requires an AT modifier on claims for active or corrective treatment, which signals that the visit is meant to produce improvement, not simply maintain a chronic condition. Without it, or without a clear initial treatment date on file, the claim is far more likely to be flagged or denied.
CMS guidance also specifies what the record needs to show:
- The exact spinal level or levels being treated.
- Exam findings or x-ray evidence supporting the subluxation diagnosis.
- A written treatment plan with a projected outcome.
- Evidence of expected or actual clinical improvement over time.
This isn’t a paperwork technicality. A federal audit found that a substantial amount in Medicare payments for chiropractic services during the sampled period did not comply with Medicare’s own requirements, almost entirely because documentation was missing or insufficient.
Reviewers repeatedly found that chiropractic claims lacked the treatment plans, exam notes, or evidence of medical necessity that Medicare requires, which drove the overwhelming majority of improper payments identified in the audit.
If your chiropractor’s office seems casual about record keeping, that’s a warning sign. It’s not just their compliance risk. It affects whether your claim gets paid at all.
How Should You Set Up Chiropractic Care to Get Covered?
A little upfront diligence saves you a denied claim and a surprise bill later.
- Confirm Medicare enrollment and participation status. You can verify this directly through Medicare.gov or by asking the office plainly.
- Ask about the AT modifier. If your treatment is meant to correct a problem, not maintain it, the claim should carry this modifier.
- Request a copy of your treatment plan and initial treatment date. Keep it. You may need it if a claim is questioned later.
- If you want a formal denial for secondary insurance, ask the chiropractor to submit the claim to Medicare anyway, even for excluded services, so you get a denial letter you can forward to a supplement plan.
Pro Tip: Never assume “the office handles billing” means the paperwork meets Medicare’s standard. Ask to see the treatment plan yourself at least once. It takes two minutes and tells you a lot about how the practice operates.
Does Medicare Advantage or Medigap Change Your Chiropractic Coverage?
Medicare Advantage plans must cover everything Original Medicare covers, including spinal manipulation, but many plans layer on extra chiropractic benefits, like a set number of visits without the usual coinsurance. These extras vary enormously by plan and are frequently subject to network restrictions or prior authorization, so a benefit that sounds generous on paper can come with real friction in practice.
- Medigap policies don’t add new services. They cover cost-sharing on what Medicare already pays for, meaning your 20% coinsurance on covered visits.
- If you rely on chiropractic care regularly, comparing how a Medicare Advantage plan’s chiropractic rider stacks up against a Medigap policy’s coinsurance coverage is worth doing before you commit to either.
- Always check the plan’s evidence of coverage document or call the plan directly. Marketing materials tend to oversimplify what’s actually covered.
Our guide to Medicare Advantage plan tradeoffs breaks down how these expanded benefits typically work across different plan types.
What Should You Watch For Before Your Next Visit?
Most denials trace back to the same handful of causes: treatment classified as maintenance rather than corrective, a missing AT modifier, or a record that simply doesn’t document medical necessity clearly enough.
- Ask your chiropractor directly: “Will you bill this as active treatment with the AT modifier, or is this maintenance care?”
- Ask your insurer: “Does my plan add chiropractic benefits beyond Original Medicare, and are there visit limits?”
- Keep every treatment plan and denial letter you receive. They matter more than you’d expect if you ever need to appeal.
Pro Tip: If a claim gets denied and you believe the care was medically necessary, you have the right to appeal through Medicare’s standard appeals process. Start with the redetermination request listed on your Medicare Summary Notice.
If you’re weighing whether a Medigap policy or a Medicare Advantage plan with chiropractic extras fits your situation better, consider getting personalized guidance on comparing these options based on how often you actually use chiropractic care and what else matters to your health coverage.
Where Can You Verify These Chiropractic Coverage Rules?
- Medicare lays out the core benefit and cost-sharing rules in plain terms.
- CMS’s billing and coding article A58412 covers the AT modifier, CPT codes, and documentation standards providers must follow.
- The HHS OIG audit report shows exactly how improper payments happen and why documentation protects you during an appeal.
An Honest Take on Chiropractic Medicare Coverage
The real story is that documentation failures, not coverage rules, cause most of the frustration beneficiaries experience. The OIG’s findings on improper chiropractic payments make that clear: the benefit itself is simple, but proving medical necessity on paper is where things fall apart.
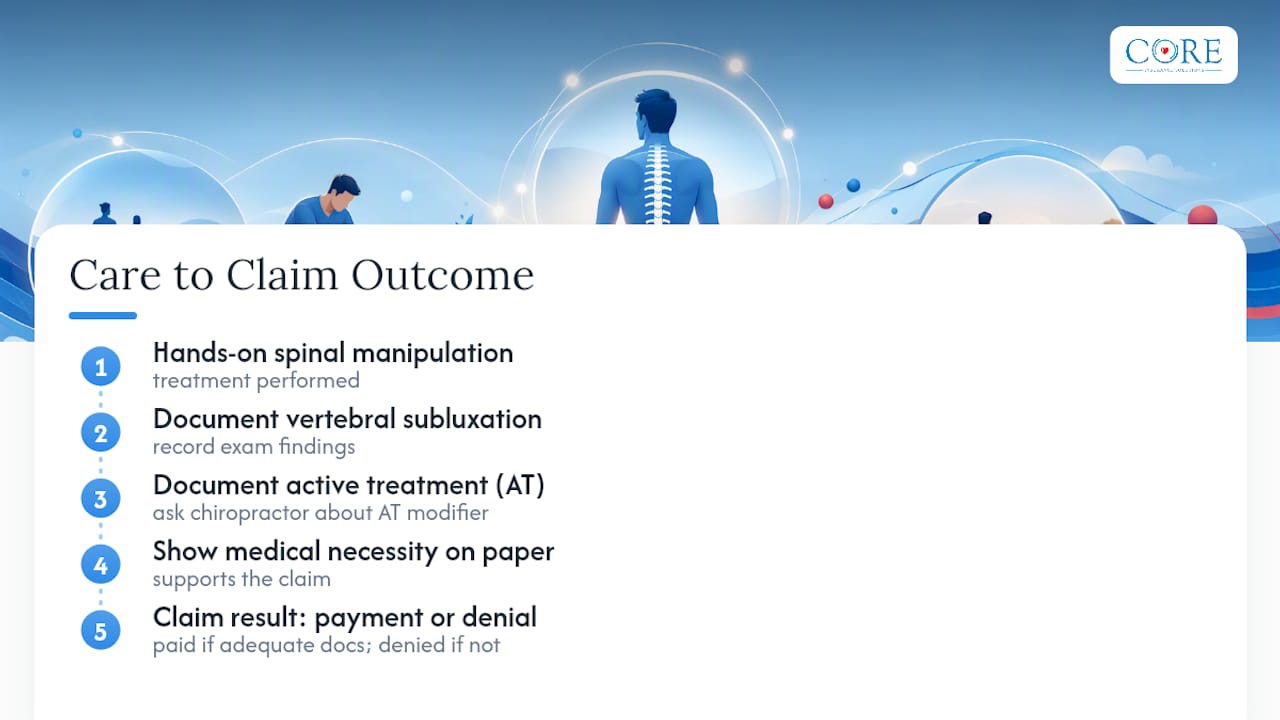
What’s overrated in most explainers is the emphasis on CPT codes and coinsurance percentages. What’s underrated is asking your chiropractor, out loud, whether they document active treatment with an AT modifier. That single question predicts claim approval better than anything else in this article.
If you take one action, make it this: before comparing Medigap and Medicare Advantage options for chiropractic coverage, get honest about how often you’ll actually use the benefit. Occasional visits make coinsurance manageable. Frequent, ongoing care changes the math entirely, and that’s exactly the kind of personalized comparison worth getting help with rather than guessing at alone.
— Core Insurance Solutions
Sources
- Coverage For Chiropractic Services
- Billing and Coding: Chiropractic Services (A58412)
- Hundreds of Millions in Medicare Payments for Chiropractic Services Did Not Comply With Medicare Requirements, A-09-14-02033